

Piggy Bank Allowance - Bomad
by Graeme P
4.4
- Safety
- 100% Safe
- Category
- Parenting
- Ratings
- 4.4
- Price
- Free
- Download
- 50.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
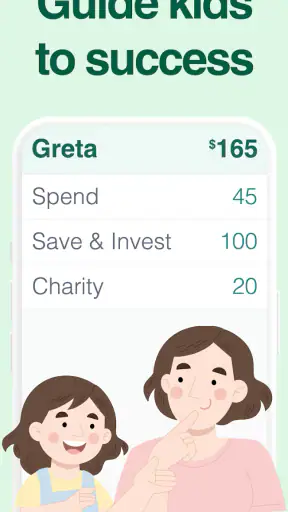
Teaching children how money works is much easier when the lesson is connected to something they already understand: finishing a chore, making a choice, waiting for a goal, or deciding whether to spend now or later. I found Piggy Bank Allowance - Bomad most useful in that everyday space. It turns an allowance into a simple visual routine, with virtual money divided between saving and spending jars or pots rather than leaving everything as an abstract promise.
This is a free parenting app from Graeme P, aimed at families who want a lightweight way to track pocket money. It is suitable for Everyone, runs on Android 9 or later, and the current version is 2.0.266. The app has reached over 50 thousand installs and holds a 4.4 average from more than 600 ratings, which gives it a reassuring amount of real-world use without making it feel like an overbuilt financial platform.
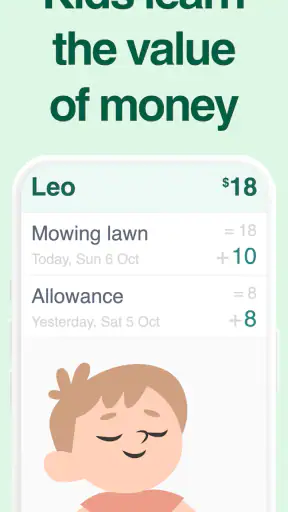
My overall impression is that its value comes from repetition. The app does not need to replace a bank account or become a complicated household ledger. Used consistently, it gives a child a visible place to see what they have earned, what they are keeping, and what they are allowed to spend. The best results come from treating it as a weekly conversation tool, not just a digital piggy bank.
How the everyday allowance routine works
I find the allowance routine works best when the app reflects an agreement the family has already made, rather than becoming the place where rules are decided on the spot. In this section, I’ll look at how to keep entries connected to real choices and make the jars useful during ordinary moments, such as a child deciding whether to buy something now or keep saving.
Start with one clear money rule
The most practical way to begin is to agree on the allowance before opening the app. Decide what counts as regular pocket money, whether chores are included, and when the amount is recorded. I would avoid changing the rules every time a child asks for something. The app can show the balance, but it cannot settle disagreements about what was promised.
Once the family rule is clear, the parent can use the app to record the allowance and let the child see the result. The jars or pots make the distinction between spending and saving easier to discuss than a single total. A child who sees all money in one balance may assume it is all available. Separating the purposes makes “I have money” different from “I can spend all of it today.”
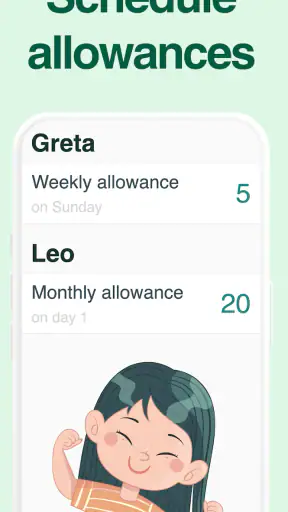
A useful first routine is to add the allowance at the same point each week, then spend a minute reviewing the jars together. That short review is more valuable than entering several weeks of transactions in a rush. The child can say what they are saving for, whether a purchase still matters, and whether the spending portion is being used as intended.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A realistic family example
Imagine a child who receives pocket money on the weekend and wants a small toy during a weekday shopping trip. Instead of answering from memory, I would open the tracker and look at the spending pot with them. If the amount is there, the purchase becomes a choice with a visible consequence. If it is not, the conversation can move toward waiting, saving, or selecting something cheaper.
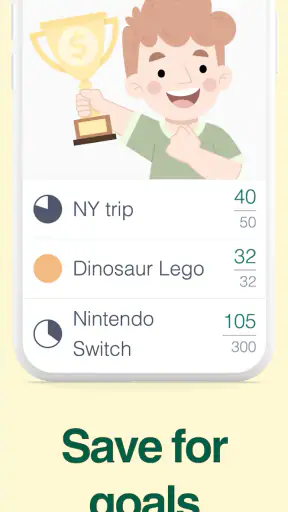
The important part is not the virtual balance by itself. It is the pause before spending. That pause creates a natural chance to ask whether the child would rather buy the item now or keep building toward a larger goal. With younger children, I would keep the language concrete: “This is what you can use today, and this is what you are keeping.” With older children, the same screen can support conversations about planning and delayed gratification.
Use the jars as decisions, not decoration
The saving and spending areas work best when each has a job. I would not move money between them simply to make the totals look tidy. If a child changes their mind about a goal, use that moment to explain why money is being moved. The transfer itself becomes a lesson: saving is flexible, but choices have consequences.
Another helpful habit is to record the allowance before discussing a requested purchase. That keeps the order consistent. First the child sees what they have earned; then they decide what to do with it. It prevents the tracker from becoming a tool used only when someone wants permission to buy something.
What parents should decide before relying on it
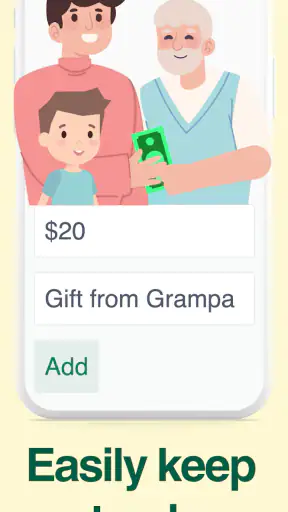
The app is a tracker, so the family still needs a simple policy for missed chores, gifts, refunds, and money received outside the normal allowance. I recommend agreeing that gifts are recorded separately in the family conversation, even if the app is used to show the resulting balance. Otherwise, children may focus on the number without understanding where it came from.
I would also decide who is responsible for entering changes. If the parent always updates the balance without showing the child, the app becomes an adult record rather than a learning aid. If the child is old enough, let them watch the entry or take part in the review. The right level of involvement depends on age, but visibility matters more than technical independence.
Settings, shortcuts, and habits that make it easier
A little preparation can prevent the tracker from feeling like another chore, especially when a family shares devices or has several children. I’ll focus on practical checks and repeatable habits that make the routine easier to maintain, while keeping the setup simple enough that the money lesson stays in view.
Check the setup before the first real payment
Before using Piggy Bank Allowance - Bomad for a live allowance, I would walk through the available settings and account arrangement calmly, rather than trying to configure everything during a disagreement about money. Look for the options that control how the jars or pots are used and make sure the labels match the words your family already uses. A child should not have to translate unfamiliar categories before understanding the balance.
It is also worth checking the device and app version before building a routine around it. The application requires Android 9 or newer, and the current release is 2.0.266. That is a practical detail for families using an older spare phone or tablet. If the child uses a shared device, make sure the family knows who will open the tracker and when, because a shared screen can be convenient but may not provide the same privacy as a personal device.
I would keep the initial setup deliberately small. Start with the basic spending and saving structure, use it for several allowance cycles, and only then decide whether the family needs a more detailed arrangement. Too many categories at the beginning can turn a simple lesson into bookkeeping. Clarity beats precision when the child is still learning what a balance means.
Build a repeatable review shortcut
The fastest experienced workflow is not necessarily entering information quickly. It is reducing the number of decisions made each time. Choose one regular review moment, use the same order, and ask the same two or three questions: what came in, what is available to spend, and what is being saved for. This makes the app feel predictable.
If the family tends to forget allowance day, connect the review to an existing routine such as a weekend breakfast or a regular household planning session. I would avoid creating a separate complicated ceremony. The tracker should fit around family life, not demand that everyone reorganize the week.
For several children, keep each child’s money discussion distinct. Even if the parent handles all entries, review one child at a time so that balances do not become a comparison contest. Different children may have different goals or responsibilities, and the point of the app is to make personal choices visible rather than rank siblings.
Use consistent language around spending and saving
One subtle advantage of jars and pots is that they give adults a stable vocabulary. I found it easier to say “the spending pot” or “the saving jar” than to talk vaguely about money being somewhere in the app. Use the same terms at the store, at home, and during the weekly review. Consistent language helps younger children connect the digital display with real coins, notes, and purchases.
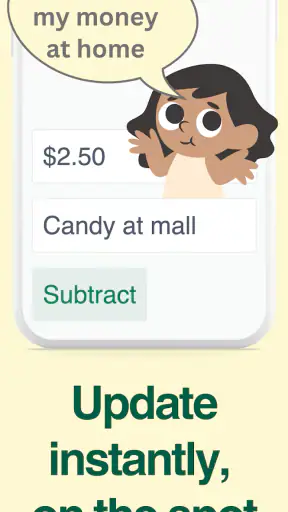
When money is spent, record the decision as soon as practical rather than waiting until the end of the month. Delayed updates weaken the connection between the purchase and the balance. If immediate entry is inconvenient, make a quick note on paper or in a family message and update the tracker during the next scheduled review. The aim is not perfect accounting; it is keeping the balance believable.
Keep paid options in perspective
The app is free to start, while in-app purchases range from $1.99 to $29.99 per item. I would use the free experience first and decide whether any paid option solves a real problem for your household. A purchase should make the routine clearer or more convenient, not become a reward that the child expects before participating.
Parents should also be clear about who controls purchases. Since this is a parenting tool, the adult should make that decision independently of the child’s allowance. The tracker’s educational purpose is strongest when the child learns to plan with the money already available, rather than treating optional app spending as part of the reward system.
Keep the visual balance honest
A common mistake is moving money between jars whenever the child wants a purchase, then leaving the original goal unchanged in conversation. That makes the display look generous but teaches little. If money moves from saving to spending, say why and acknowledge that the saving target will take longer. The app is most useful when its visual simplicity reflects an honest choice.
Likewise, do not use the tracker as a punishment screen. Removing money impulsively may create fear around the balance instead of understanding. If chores and allowance are connected, settle the rule in advance and apply it consistently. The application can display the result, but the family agreement should explain it.
Where the app is strong, and where its limits matter
The app’s visual approach is a good fit for learning the difference between saving and spending, but it is not meant to handle every kind of family finance. I’ll weigh that focused role against physical cash, spreadsheets, and more comprehensive tools, so it is easier to tell when the app suits your household and when another approach may work better.
It is better than mental arithmetic for young learners
The usual alternative is a parent remembering the allowance, a child asking how much they have, and everyone trying to reconstruct previous spending. That method works until the family gets busy. Piggy Bank Allowance - Bomad gives the conversation a stable reference point. The jars make the difference between saving and spending easier to see than a handwritten total.
A physical piggy bank still has advantages. It gives a child something tangible to handle and can make saving feel real. Cash also works without a screen. For a very young child who is still learning coins, I would combine a physical container with the app rather than choosing only one. The digital tracker is more useful for continuity and review; the physical money provides a sensory lesson the screen cannot reproduce.
A spreadsheet can offer more detailed records and custom calculations, but it usually asks more from the parent and is less inviting for a child. A full budgeting app may be appropriate for an older teenager managing several expenses, yet it can be excessive for a basic allowance. This application sits in the middle: more structured than memory or a paper note, but less intimidating than household finance software.
It is not a replacement for real financial independence
I would not choose this as the main financial tool for a teenager who needs banking, card management, account transfers, or a detailed spending history. Its strength is the allowance conversation, not full personal finance administration. Families looking for those functions should consider a dedicated youth banking or budgeting product instead.
It may also be a poor fit if every child in the household needs a highly individualized reward system with complex rules. The more exceptions a family creates, the more likely the tracker will need manual explanation around it. In that situation, a carefully designed spreadsheet or a shared household system may offer more flexibility, even if it is less friendly for children.
Remember that the display does not make money move
The virtual balance is a representation of the family’s agreement. It does not turn into spendable cash simply because the spending pot shows an amount. Parents still need to provide the money, supervise purchases where appropriate, and decide how digital or cash payments are handled. This distinction is especially important when children assume that a screen balance works like a bank card.
I would explain this at the beginning: the app helps us track the money, while the parent still handles the actual payment. That one sentence prevents a great deal of confusion. It also makes the tool suitable for families who use cash, occasional digital purchases, or a mixture of both, provided the adult keeps the record current.
Privacy and shared-device habits deserve attention
Because the tracker concerns children and money, I would treat the phone or tablet as a family object rather than leaving the child to manage everything without guidance. Use a shared review when that is appropriate, and avoid displaying balances in situations where siblings or visitors might turn them into a source of embarrassment. The app can support openness, but openness should still be respectful.
This is another reason I prefer a short scheduled review to constant checking. The child learns that money is something to think about at sensible moments, not something to monitor anxiously throughout the day. A calm routine makes the educational benefit clearer.
Who will appreciate it most
I think the strongest audience is a parent introducing allowances for the first time, especially when the child needs a visual explanation of saving versus spending. It also suits families that already give pocket money but keep losing track of what was promised or where it went. The free entry point makes it easy to test the routine without committing to a larger financial system.
It is less suitable for someone who wants investment tracking, bank synchronization, detailed reports, or a fully automated allowance process. It is also not ideal for a parent who does not want to discuss the rules behind each balance. The app can simplify the record, but it cannot replace consistency, follow-through, or a shared understanding of what the money represents.
My verdict after using it as a family habit
Piggy Bank Allowance - Bomad succeeds because it keeps the central lesson visible: money can be divided according to purpose. I like that the saving and spending jars give children something concrete to discuss without forcing parents into a full budgeting system. The app is simple enough for a regular allowance routine and flexible enough to support real choices about waiting, buying, and changing goals.
Its limitations are closely tied to that simplicity. Parents must enter or confirm the figures, explain exceptions, and make sure the virtual balance matches the family’s actual arrangement. It will not replace cash, a bank account, or a detailed teen budget. If you expect automation or advanced financial records, you will probably outgrow it quickly.
For the right household, though, that modest scope is a benefit. I would install it, set up only the essential jars, agree on one allowance routine, and review the balance at the same time each week. After a few cycles, I would adjust the habit rather than immediately adding complexity. The app is at its best when it quietly supports a conversation that families can repeat.
Developed by Graeme P, it is a sensible free parenting app for families who want children to see the difference between money available now and money reserved for later. The Everyone rating makes it approachable for a broad family audience, while the optional purchases mean parents can decide for themselves whether extra spending is worthwhile. My recommendation is positive, with one condition: use it as a shared learning tool, not as an automatic solution. When the parent and child look at the jars together and make deliberate choices, the simple design becomes genuinely useful.
Pros
- Simple way to track children’s allowances and savings goals
- Encourages kids to learn budgeting and money management
- Parents can monitor payments and balances in one place
- Useful for setting regular allowance schedules and reminders
- Clean interface that is easy for children to understand
Cons
- May require both parent and child accounts for full functionality
- Limited value for families that do not use regular allowances
- Some features may depend on in-app purchases or subscriptions
- Children may need parental help when first setting up the app
- Digital balances do not replace real-world lessons about spending
FAQs for Piggy Bank Allowance - Bomad
What is Piggy Bank Allowance - Bomad, and who is it designed for?
Piggy Bank Allowance - Bomad is an allowance-management app designed to help parents organize children’s pocket money and teach basic financial responsibility. Parents can typically use it to record allowances, set tasks or expectations, and track whether money has been earned or paid. It is most suitable for families looking for a simple digital alternative to managing cash-based allowances.
How does Piggy Bank Allowance - Bomad help children learn about money?
The app encourages children to connect money with regular allowances, completed responsibilities, and saving habits. By viewing their balance and tracking incoming or outgoing amounts, children can begin to understand budgeting and delayed gratification. However, it works best when parents discuss spending choices with them, since the app supports financial education but does not replace real guidance or age-appropriate conversations.
Can parents customize allowances, chores, or payments in the app?
Customization is one of the main reasons families may choose Piggy Bank Allowance - Bomad. Depending on the device version and available features, parents can usually define allowance amounts, payment schedules, tasks, or rewards to match their household routine. Before downloading, it is worth checking the current app-store description because specific options, account requirements, and supported payment methods may change.
Does Piggy Bank Allowance - Bomad handle real money or transfer funds to a child?
Users should not automatically assume that recording an allowance in the app means real money is transferred. Apps in this category may function primarily as digital ledgers, while actual payments are handled separately by parents through cash, bank transfers, or another service. Review the app’s current permissions, payment information, and store listing carefully to confirm exactly what financial functions are supported.
Is Piggy Bank Allowance - Bomad safe and suitable for children?
The app can be useful for family budgeting, but parents should remain responsible for account setup, privacy decisions, and financial discussions. Check whether the app requires registration, collects personal information, displays advertising, or includes optional purchases. Children should use it with parental supervision, especially if real payment details or household financial information are entered. Always review the latest privacy policy and age rating before installation.

Piggy Bank Allowance - Bomad
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via info@bomad.app, visit https://bomad.app, or review their https://bomad.app/privacy-policy.










